
[Founder Securities] The "Moderate Risk-Taking" Factor: Decoding the "Volume-First" Logic via Intraday Price-Volume Dynamics
2022-04-12_方正证券_多因子选股系列研究之一:成交量激增时刻蕴含的alpha信息
This report introduces the "Moderate Risk-Taking" (适度冒险) factor, a novel quantitative stock-selection tool based on marginal changes in intraday trading volume. By synthesizing "Dazzling Volatility" and "Dazzling Return" during periods of surging volume, the method achieves a significant Rank IC of -8.89% and an annualized long-short return of 37.46% in the A-share market.
TL;DR
In the A-share market, the adage "Volume precedes Price" is a cornerstone of technical analysis. This research by Founder Securities moves beyond simple volume tracking to identify "Surge Moments" and "Dazzling 5 Minutes." By measuring how "moderately" a stock reacts to sudden volume spikes compared to its peers, the authors constructed the Moderate Risk-Taking Factor, achieving an impressive 37.46% annualized long-short return with a remarkably high monthly win rate of nearly 88%.
Problem & Motivation: The Trap of Extreme Reactions
Why do some stocks skyrocket on high volume only to crash later, while others trend steadily? The researchers argue that:
- Underreaction: If volume surges but price stays flat, the "good news" isn't being recognized by the market.
- Overreaction: If volume surges alongside extreme price swings, it indicates a "herd mentality" where investors are taking excessive risks, leading to potential reversals.
The "sweet spot" lies in Moderate Risk-Taking—where the market recognizes the information but processes it without irrational exuberance.
Methodology: Identifying the "Dazzling" Moments
1. Defining the "Surge Moment"
The model scans intraday minute-level data (excluding market open and close). A "Surge Moment" is defined as any minute where the increase in volume () exceeds the daily mean plus one standard deviation:
2. The "Dazzling 5 Minutes"
The 5-minute window starting from a "Surge Moment" is where investor attention is most concentrated. The authors calculate two proxies here:
- Dazzling Volatility: Standard deviation of returns within these 5 minutes.
- Dazzling Return: Simple return within the surge minute.
3. Calculating "Moderation"
The core innovation is the "Moderate" transformation. Instead of looking for high or low values, the factor looks for values close to the market average: This captures the distance from the market's average reaction.
 Figure 1: Illustration of Intraday "Surge Moments"
Experiments & Results: Robust Alpha Generation
The composite "Moderate Risk-Taking" factor was tested on the entire A-share universe from 2013 to 2022.
- Factor Performance: The factor shows a strong negative correlation with future returns (lower distance from the mean = better performance).
- Style Neutralization: Even after stripping away effects from Size, Momentum, Volatility, and Liquidity, the "Pure" factor remains highly effective.
- Market Universality: While it performs best in the CSI 500 (mid-cap), it shows significant predictive power in both Blue-chips (HS 300) and Small-caps (CSI 1000).
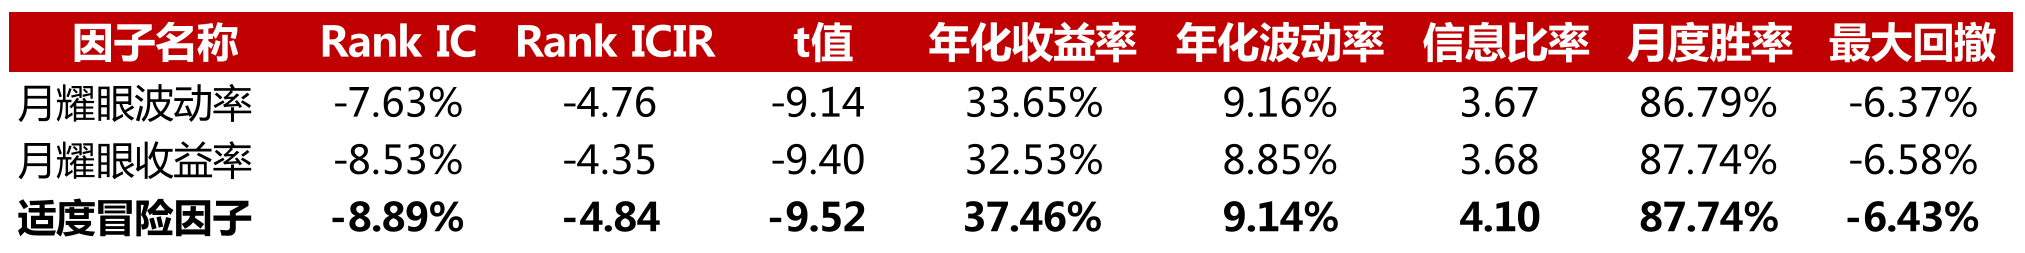 Figure 2: Statistical performance of the Moderate Risk-Taking Factor
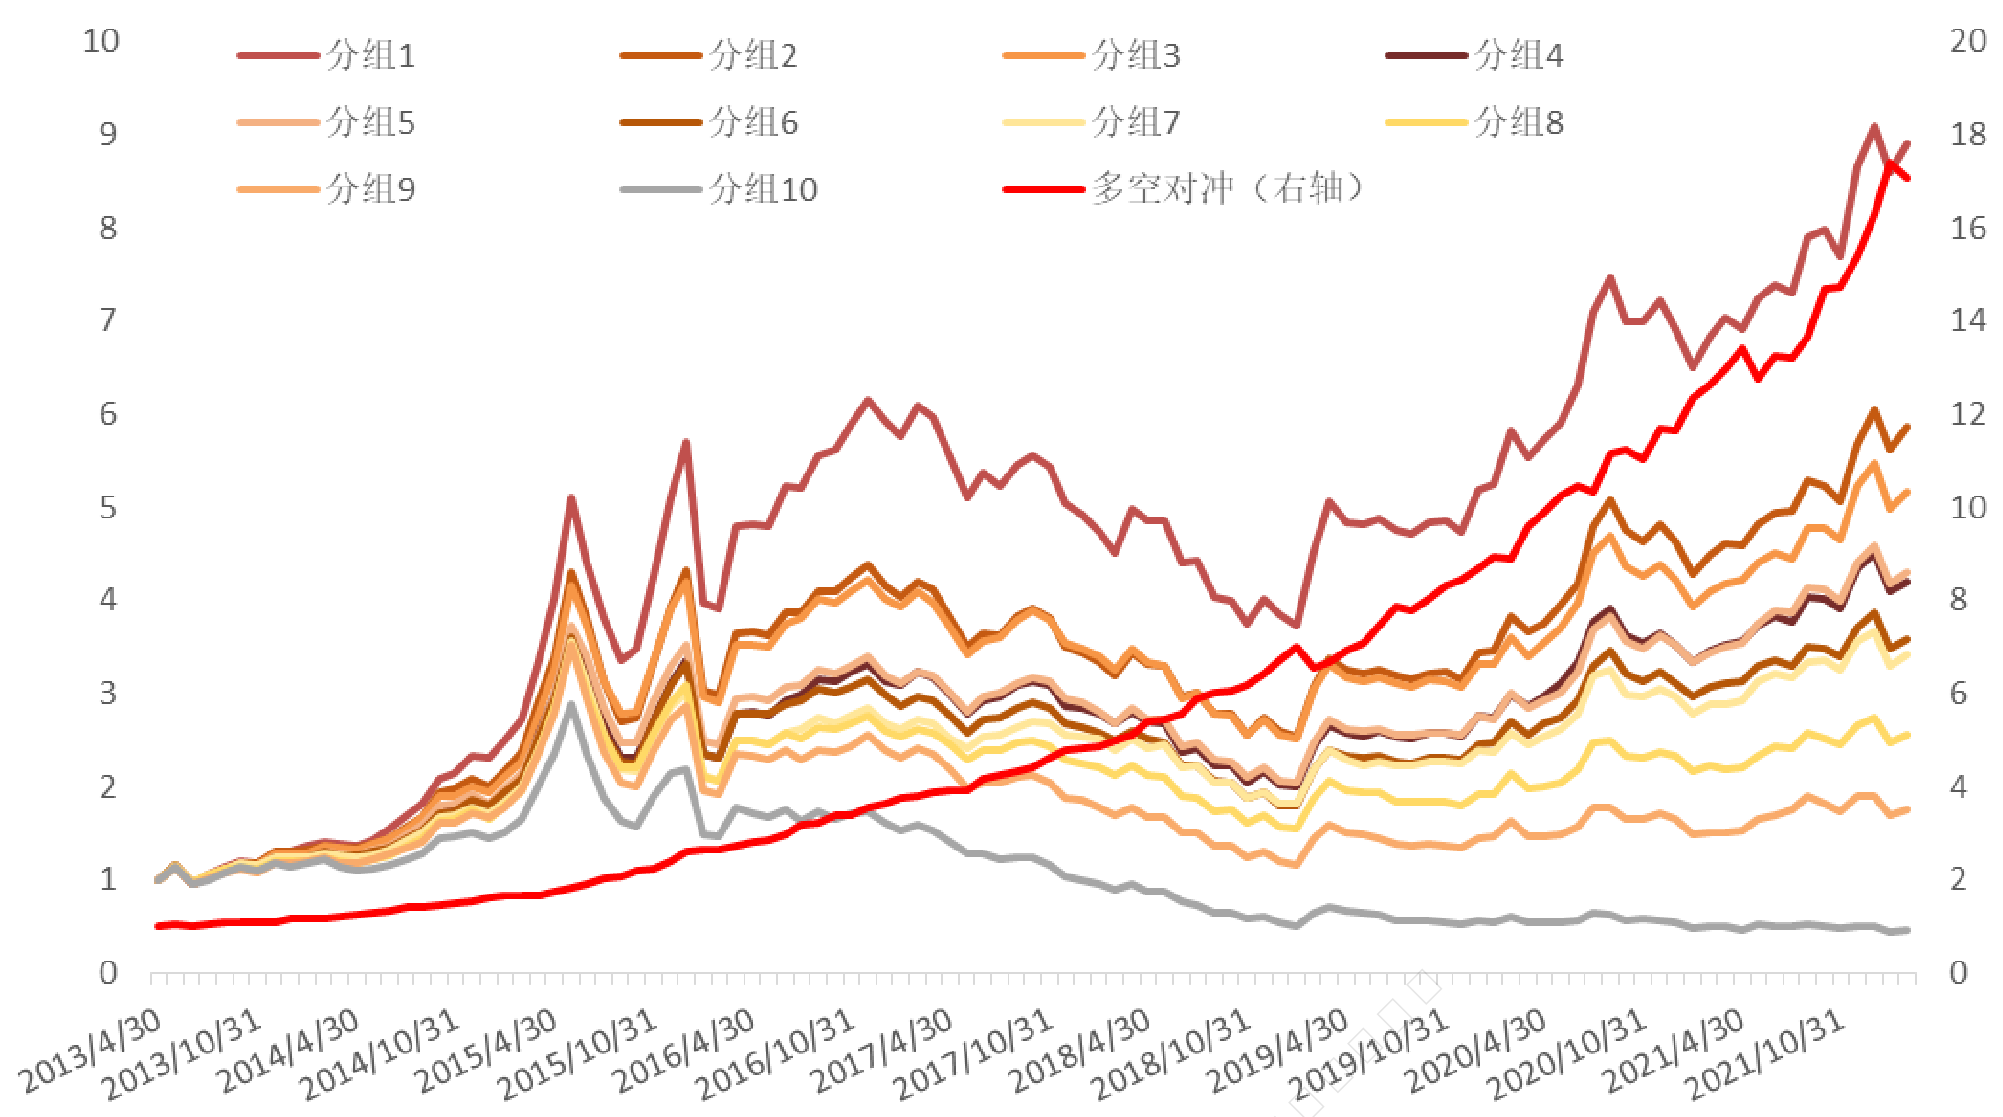 Figure 3: Long-short equity curves showing steady alpha growth
Critical Analysis & Conclusion
Takeaways
The "Moderate Risk-Taking" factor is a sophisticated behavioral finance implementation. It successfully quantifies the "Goldilocks principle" of market returns—not too quiet, not too loud, but just right. This suggests that in the noise-heavy A-share market, rational consensus is a better predictor of medium-term gains than explosive hype.
Limitations
- High-Frequency Dependency: The factor requires 1-minute bar data, which increases the data processing burden for many practitioners.
- Market Impact: As a volume-based factor, large-scale execution based on this signal might disturb the very "moderate" behavior it seeks to exploit.
Future Work
The sensitivity analysis shows the factor is robust to 3-minute, 4-minute, or 5-minute windows. Future research could investigate whether applying machine learning to the shape of the volume surge (e.g., using CNNs on intraday charts) could further refine the detection of "moderate" vs. "extreme" participants.