
Beyond Financial Ratios: Why Corporate Governance is the Missing Piece in Bankruptcy Prediction
European journal of operational research
This study evaluates the predictive power of combining 7 categories of Financial Ratios (FRs) and 5 categories of Corporate Governance Indicators (CGIs) for bankruptcy prediction. Using a Taiwanese dataset, the researchers identified that an SVM model coupled with Stepwise Discriminant Analysis (SDA) achieves SOTA performance by integrating specific governance metrics with traditional financial data.
TL;DR
Predicting corporate bankruptcy isn't just about reading the balance sheet anymore. This study proves that integrating Corporate Governance Indicators (CGIs)—specifically board and ownership structures—with traditional financial ratios significantly sharpens the accuracy of Support Vector Machine (SVM) models. While the "Solvency" and "Profitability" of a firm remain its pulse, its governance is the underlying DNA that determines long-term survival.
Problem & Motivation: The Tunnel Vision of Financial Modeling
For decades, financial institutions relied almost exclusively on Financial Ratios (FRs) like liquidity and debt-to-equity. However, the 2008 crisis and subsequent corporate scandals revealed a fundamental truth: a company can appear financially solvent on paper while its internal governance is crumbling.
Previous research suffered from two major gaps:
- Over-complication of Algorithms: Researchers were obsessed with "what" model to use (the latest ML gimmick) rather than "what" data to feed it.
- Lack of Feature Synergy: There was no clear consensus on which specific governance categories truly provide "discriminatory power" when paired with financial data.
Methodology: The Search for Discriminatory Power
The researchers conducted a massive bake-off involving five prediction models and five feature selection techniques. They utilized a real-world dataset from Taiwan (1999–2009) to test the impact of 7 FR categories and 5 CGI categories.
The Core Framework
The authors emphasized the SVM (Support Vector Machine) model combined with SDA (Stepwise Discriminant Analysis).
The figure above illustrates the systematic approach: from data collection and normalization to the rigorous 10-fold cross-validation of multiple classifiers.
Key Insights: What Actually Matters?
By systematically removing one category at a time (Ablation Study), the researchers identified the "Mount Rushmore" of bankruptcy features:
- Financial Essentials: Solvency and Profitability. Without these, the model's accuracy degrades instantly.
- Governance Essentials: Board Structure and Ownership Structure.
- The Surprise: Interestingly, features like "Cash Flow per Share" or "Employee Growth" were often redundant when the core solvency and governance metrics were already present.
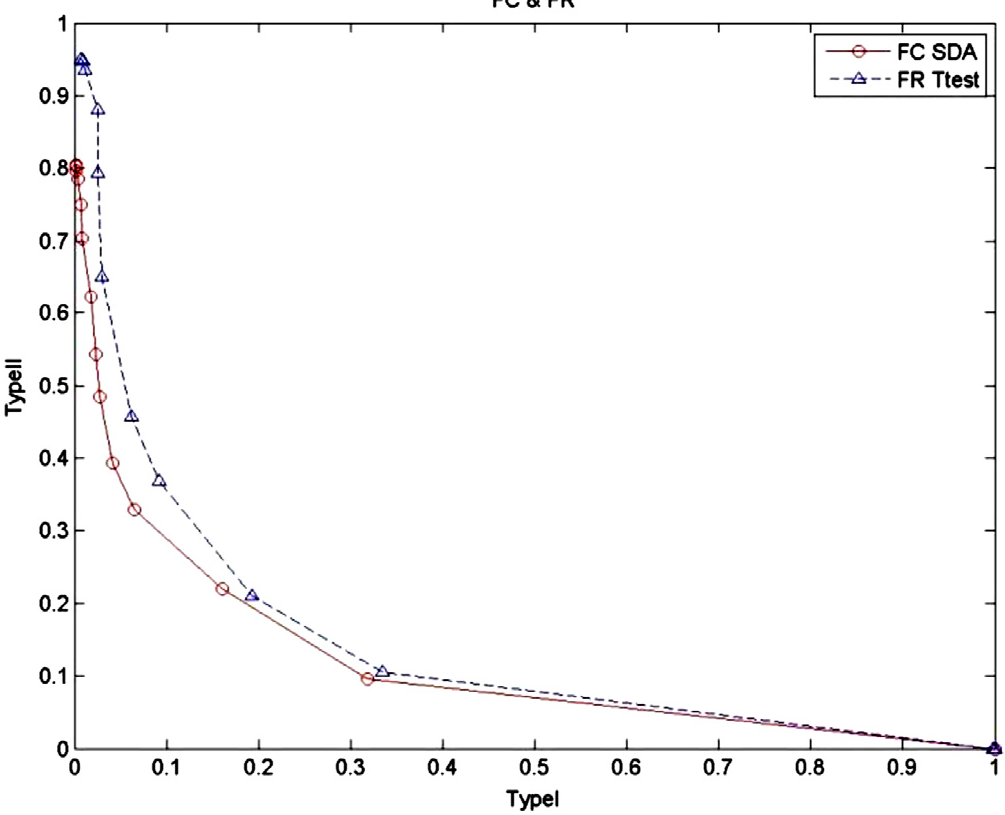
As shown in the ROC curves, models represented by the 'FC' (Financial + Corporate) dataset consistently show a larger Area Under the Curve (AUC) compared to 'FR' (Financial Ratio) only models, especially when misclassification costs are high.
The "Market Dependency" Caveat
A fascinating finding in this study is the China Validation. When the same method was applied to the Chinese market, the CGIs performed poorly. Why?
- Ambiguous Definitions: China's "Special Treatment" (ST) companies don't always align with traditional bankruptcy definitions.
- State Ownership: Many Chinese firms are government-linked, making standard "Board Structure" indicators less representative of actual risk compared to private firms in Taiwan.
Deep Insight & Conclusion
Takeaway
The integration of governance data effectively reduces Type I Errors (failing to predict a bankruptcy), which is the most expensive mistake a bank can make. If you are building a credit risk model, ignoring the number of seats controlled by ultimate controllers or the frequency of board turnover is leaving money on the table.
Limitations
The study is constrained by geographical regulatory frameworks. Governance behaviors in bank-based economies (like Germany or Japan) may behave differently than the market-based indicators analyzed here.
Future Outlook
The next frontier is likely Alternative Data. If corporate governance adds this much value, imagine what real-time sentiment analysis from employee reviews or ESG (Environmental, Social, and Governance) scores could do to fortify these models.